HAC News: January 7, 2015

HAC News Formats. pdf

January 7, 2015
Vol. 44, No. 1

• New Congress convenes • Obama announces lower FHA mortgage insurance rate • Rural housing program eligibility changes effective February 2 • HUD proposes regulatory changes for vouchers, public housing, and other programs • Changes to BIA’s Housing Improvement Program proposed • Final credit risk retention rule defines QRM as QM • Family Self-Sufficiency Programs merged • Housing tax credit properties can achieve deep affordability without vouchers, report says • Paper explores connections between rural community and rural poverty • HAC webinar on seniors set for January 13

January 7, 2015
Vol. 44, No. 1

NEW CONGRESS CONVENES. In the new 114th Congress starting this week, some of the committee leadership posts are clear. Rep. Harold Rogers (R-KY) continues as chairman of the House Appropriations Committee, and Sen. Thad Cochran (R-MS) will lead the Senate appropriations panel. Rep. Jeb Hensarling (R-TX) continues as head of the House Financial Services Committee, and Sen. Richard Shelby (R-AL) will be the new chairman of the Senate Banking Committee. On the Democratic side, Reps. Nita Lowey of NY and Maxine Waters of CA will continue as the ranking minority members on House Appropriations and Financial Services. In the Senate, Barbara Mikulski (D-MD) will be the top Democrat on Appropriations. Other Democratic spots and most subcommittee leaders have not yet been announced. As reported in the HAC News, 12/10/14, Rep. Robert Aderholt (R-AL) will continue as chairman of the House Appropriations Subcommittee on Agriculture and Rural Development, and Rep. Mario Diaz-Balart (R-FL) will be the new chairman of the Subcommittee on Transportation-HUD.

OBAMA ANNOUNCES LOWER FHA MORTGAGE INSURANCE RATE. The rate will drop by 0.5 percentage point from 1.35% to 0.85%. The President’s statement says the change will save an average of $900 annually for new borrowers and also reiterates support for housing finance reform.

RURAL HOUSING PROGRAM ELIGIBILITY CHANGES EFFECTIVE FEBRUARY 2. USDA RD will implement a 2014 Farm Bill’s provision making places ineligible that were formerly considered rural, but have populations over 35,000 as of the 2010 Census. See RD’s “future eligible areas” maps. Applications from these places will be processed if completed before February 2. Contact an RD office or Mike Feinberg, HAC, 202-842-8600.

HUD PROPOSES REGULATORY CHANGES FOR VOUCHERS, PUBLIC HOUSING, AND OTHER PROGRAMS. Updates would put recent statutory changes into effect and would align program requirements for Housing Choice Vouchers (tenant- and project-based) and public housing. Section 202, Section 811, and other multifamily housing programs are also affected, as well as HOME, the Continuum of Care program, and HOPWA. Comments are due March 9, 2015. Contacts for each program are listed in the notice.

CHANGES TO BIA’S HOUSING IMPROVEMENT PROGRAM PROPOSED. HIP provides grants to tribal members for repair, renovation, or replacement of existing housing. Comments are due March 6 on changes that are intended to align the program with other federal requirements, allow leveraging of housing funds, and expedite processing of waiting lists. BIA will host consultation sessions with tribes in February; for details, visit https://www.bia.gov/WhoWeAre/AS-IA/ORM/HIP/index.htm. Contact Mr. Les Jensen, BIA, 907-586-7397.

FINAL CREDIT RISK RETENTION RULE DEFINES QRM AS QM. “Qualified residential mortgages” are exempt from the Dodd-Frank Act’s requirement for lenders to retain part of the credit risk of assets that collateralize asset-backed securities. Federal regulators have adopted a definition proposed in 2013 (see HAC News, 9/25/13): a QRM is the same as a Consumer Financial Protection Bureau “qualified mortgage” and need not have a 20% downpayment. Also exempt are mortgages made by state HFAs, CDFIs, CHDOs (for HOME-funded projects), small-volume nonprofits, and others. Contact Ronald P. Sugarman, FHFA, 202-649-3208.

FAMILY SELF-SUFFICIENCY PROGRAMS MERGED. Implementing a provision in its FY14 appropriations act, HUD has unified the programs, formerly separate for participants with Housing Choice Vouchers and those in public housing. Contact Anice Chenault, HUD, 202-402-2341.

HOUSING TAX CREDIT PROPERTIES CAN ACHIEVE DEEP AFFORDABILITY WITHOUT VOUCHERS, REPORT SAYS. A new National Low Income Housing Coalition publication, Aligning Federal Low Income Housing Programs with Housing Need, says Low Income Housing Tax Credit properties rarely serve extremely low-income households (at or below 30% of area median income) without vouchers, but presents five case studies of innovative strategies that do not use vouchers.

PAPER EXPLORES CONNECTIONS BETWEEN RURAL COMMUNITY AND RURAL POVERTY. “Understanding Connections between Rural Communities and Family Well-Being: A Study of Hampton, Iowa,” published by the Carsey School of Public Policy at the University of New Hampshire, examines the role of “place” in shaping the futures of rural residents, particularly low-income residents.

HAC WEBINAR ON SENIORS SET FOR JANUARY 13. Register now for “Rural Seniors and Their Homes: Planning for a Rapidly Aging Rural America” to learn more about the demographic, economic, and housing trends of seniors and near-seniors in rural America as well as their housing options.

USDA Rural Development Obligations FY 15 – November

Download complete report (Through November FY 2015)

thumb usda-obs-cover

The Housing Assistance Council (HAC) presents this month’s report on Fiscal Year 2015 USDA Rural Housing program obligations.

In November, USDA operated under a Continuing Resolution (CR) which provided funding through December 11, 2014 based on last year’s levels in the Consolidated Appropriations Act, 2014. A final appropriations bill was passed and signed into law on December 16, 2014. Most rural housing programs received funding levels similar to FY 2014. Section 523 TA grants increased by about $2.5 million. The MPR demonstration program decreased about $3 million. Section 542 Vouchers decreased by about $1 million.

As of the end of November, USDA obligated 29,060 loans, loan guarantees, and grants totaling about $3.85 billion. This is about 10,000 more obligations than the same time last year. Most of the increase in obligations occurred in the Section 502 guaranteed loan program.

Single Family Housing Program Highlights

The Section 502 Guaranteed loan program, the largest of the Single Family Housing programs, obligated $3.8 billion (27,989) in loan guarantees. Obligations have been averaging about $1.9 billion per month over the last six months.

For the Section 502 Direct program, there have been about $40.3 million (347 loans) in loan obligations so far in FY 2015; this is about $14 million (139 loans) more than last year. Very low-income (VLI) loan obligations as a percentage of the total dollars obligated for the program has increased to almost 37 percent.

The Section 504 Repair and Rehabilitation programs obligated 226 loans representing $1.2 million and 490 grants representing $2.9 million. These are similar to the obligation levels for the programs at the same time last year.

Multi-Family Housing Programs

The Section 538 loan guarantee program shows 8 obligations totaling $6.7 million, an increase over the October level of 3 loans, $3.3 m. October obligations for this program were missing in our report from last month.

Rental Assistance obligations were somewhat higher than last year at the same time with almost 60 thousand obligations representing $268 million. This compares to about 60 thousand units at $244 million last year.

Section 542 vouchers totaled 780 obligations representing $2,584,800, about 30 percent higher than this time last year.

Download the combined document.

Individual Program Files

Summary Files

Summary of Rural Development Obligations
Summary Data of Rural Development Obligations Compared to Previous Year
Summary Data of Rural Development Obligations Compared to Previous Month
USDA Rural Development Eligible Areas

Single Family Housing Program Obligations

Section 502 Direct Homeownership Total Obligations
Section 502 Direct Homeownership Low and Very Low Obligations
Section 502 Guaranteed Homeownership Obligations
Section 504 Total Home Rehab Obligations
Section 523 Self-Help Technical Assistance Grant Obligations

Multi-Family Housing Program Obligations

Section 514/516 Farm Labor Housing Obligations
Section 515 Rental Housing Obligations
Section 521 Rental Assistance Obligations
Section 533 Housing Preservation Obligations
Section 538 Guaranteed Rental Obligations
Multifamily Housing Tenant Voucher Obligations
Multifamily Housing Revitalization Demonstration Program

Unallocated Program Obligations

Section 306 Water/Wastewater Grant Obligations
Section 509 Compensation for Construction Defects
Multifamily and Single-family Housing Credit Sales

* The Rural Housing Service (RHS) monthly obligation reports are produced by the Housing Assistance Council (HAC) 1025 Vermont Ave., NW, Suite 606, Washington, DC 20005. The monthly figures derive from HAC tabulations of USDA –RHS 205c, d, and f report data. For questions or comments about the obligation reports, please contact Michael Feinberg at 202-842-8600 or michael@ruralhome.org.

HAC News: December 22, 2014

HAC News Formats. pdf

December 22, 2014
Vol. 43, No. 25

• FY15 spending bill signed into law • Tax extenders bill includes LIHTC and NMTC • FHFA activates obligation to National Housing Trust Fund • FHFA interim rule prohibits pass-through of NHTF and CMF costs • Preliminary assessment tool released for USDA multifamily transfers • Regulations issued to replace several OMB circulars • RUS offers rural broadband grants • USDA prohibits age discrimination • Regulations change rural definition for single-family housing programs • Half of Native American mortgage applicants were denied in 2013 • New report suggests housing policy consider changes over time • Rural nonprofits have broad impact, report says • HAC summarizes data on homelessness • Conference photos and other materials now online

December 22, 2014
Vol. 43, No. 25

FY15 SPENDING BILL SIGNED INTO LAW. The “cromnibus” final spending bill for FY15 funds the Department of Homeland Security through February 27 and the rest of the government, including USDA and HUD, have full-year appropriations through September 30. For housing programs’ spending levels, see HAC News, 12/10/14.

TAX EXTENDERS BILL INCLUDES LIHTC AND NMTC. H.R. 5771, passed by the House and Senate, provides a minimum 9% Low Income Housing Tax Credit rate and authorizes the New Markets Tax Credit for calendar year 2014. Since 2014 LIHTC allocations have already been distributed, the bill has little impact on that program.

FHFA ACTIVATES OBLIGATION TO NATIONAL HOUSING TRUST FUND. On December 11, Federal Housing Finance Agency director Mel Watt instructed Fannie Mae and Freddie Mac to begin setting aside funds for the National Housing Trust Fund and Capital Magnet Fund. The NHTF will fund housing, mostly rental and mostly for extremely low-income households. The CMF provides funds to CDFIs and nonprofits to finance affordable housing and related economic development and community service facilities. HUD, which will operate the NHTF program, published proposed regulations in October 2010; Secretary Julián Castro announced final rules will be issued soon. The National Low Income Housing Coalition estimates the first NHTF funds will be allocated to states in early 2016.

FHFA INTERIM RULE PROHIBITS PASS-THROUGH OF NHTF AND CMF COSTS. A Federal Housing Finance Agency interim final rule provides that the cost of Fannie Mae’s and Freddie Mac’s NHTF and CMF allocations may not be transferred to mortgage originators. Comments are due January 15. Contact Alfred M. Pollard, FHFA, 202-649-3050.

PRELIMINARY ASSESSMENT TOOL RELEASED FOR USDA MULTIFAMILY TRANSFERS. Applicants are asked to use this tool before requesting ownership transfers and MPR-related transfers, to gauge if the proposed transactions will conform to USDA RD’s underwriting standards. Accompanying policy clarifications are being drafted for RD’s hand-book HB-3-3560. A separate tool will be provided for stay-in owner transactions. RD will conduct a webinar in January; HAC will report details when they are available. Request the tool from, or send comments to, Beverly Casey or an RD state office.

REGULATIONS ISSUED TO REPLACE SEVERAL OMB CIRCULARS. All federal award-making agencies, including USDA RHS, HUD, and VA, jointly issued an interim final rule that will apply to future federal awards. The rule implements the Office of Management and Budget’s Uniform Administrative Requirements, Cost Principles, and Audit Requirements for Federal Awards, superceding several circulars including A-110, A-122, and A-133. Comments are due February 17. Contact Victoria Collin or Gil Tran, OMB, 202-395-3993. More resources are at https://cfo.gov/COFAR./.

RUS OFFERS RURAL BROADBAND GRANTS. Nonprofits, for-profits, coops, limited liability companies, tribes, states, and local governments can apply by February 17 for Community Connect grants to provide broadband service to currently unserved areas. Contact Shawn Arner, RUS, 202-720-0800.

USDA PROHIBITS AGE DISCRIMINATION. Recipients of USDA funds may not discriminate based on age, except when age distinctions are necessary to achieve a program’s purpose. Comments are due January 9. Contact Anna G. Stroman, 202-205-5953.

REGULATIONS CHANGE RURAL DEFINITION FOR SINGLE-FAMILY HOUSING PROGRAMS. The amendments implement revisions adopted in the 2014 Farm Bill (see HAC News, 2/5/14). Contact Shantelle Gordon, RHS, 202-205-9567.

HALF OF NATIVE AMERICAN MORTGAGE APPLICANTS WERE DENIED IN 2013. An Indian Country Today article reports that Home Mortgage Disclosure Act data show 51% of Indians and Native Alaskans applying for mortgages received them, while the rate for Native Hawaiians was 57%.

NEW REPORT SUGGESTS HOUSING POLICY CONSIDER CHANGES OVER TIME. Housing More People More Effectively through a Dynamic Housing Policy, published by the Bipartisan Policy Center, recommends moving from a static, transaction-focused housing policy to one that focuses on a broader time horizon and considers how things change over time at the property, household, and neighborhood levels.

RURAL NONPROFITS HAVE BROAD IMPACT, REPORT SAYS. The National Rural Housing Coalition’s Impact Report: The Economic and Human Impact of Nonprofit Organizations on Rural America estimates that in 2013 alone, nonprofit organizations generated $380 million in economic activity and created over 40,000 jobs in rural communities.

HAC SUMMARIZES DATA ON HOMELESSNESS. “Homelessness Declines but is Still Difficult to Assess in Rural Areas” is based on data released by HUD (see HAC News, 11/12/14).

CONFERENCE PHOTOS AND OTHER MATERIALS NOW ONLINE. Visit https://Ruralhome.org/calendar/nrhconf/1061-materials-from-the-2014-hac-conference for links to workshop materials via the conference app, photos, and videos.

HAC News: December 10, 2014

HAC News Formats. pdf

December 10, 2014
Vol. 43, No. 24

• Congress nears final action on 2015 spending • House passes NAHASDA reauthorization • New appropriations panel chairs announced • Mensah sworn in at USDA • USDA issues limited English proficiency guidance • VA adopts final HISA program regulation • HUD extends deadline for 202/811 comments • Email list for USDA direct single-family housing loan programs launched • HAC honors rural housing leaders • HAC Rural Housing Conference materials available • Rural Voices covers poverty in rural America • New HAC report examines senior housing

December 10, 2014
Vol. 43, No. 24

CONGRESS NEARS FINAL ACTION ON 2015 SPENDING. A wrap-up spending bill for FY 2015 was unveiled by House appropriators on December 9. The bill (H.R. 83) has been labeled a “cromnibus” because it provides a continuing resolution (CR) for the Department of Homeland Security through February 27 and an omnibus for the rest of the government, including USDA and HUD, through September 30. Republicans opposed to the President’s recent actions on immigration will look further at that issue in DHS appropriations when the new Congress convenes in January. The House is expected to pass the bill this week but the current government-wide CR expires December 11, so another two- or three-day CR may be needed for final Senate consideration. Check HAC’s web site for updates.

USDA. Rejecting most of the Administration’s FY 2015 budget proposals, H.R. 83 retains funding for Section 502 direct loans and the Rural Community Development Initiative and increases Section 523 self-help. It does not adopt the Administration’s request for minimum rents but does prohibit renewal of RA contracts that use up their funding before their full 12-month terms, and directs USDA to report on RA implementation by June 1, 2015. The bill also continues the pilot packaging program for Section 502 direct loans. The table below has details. [tdborder][/tdborder]

USDA Rural Dev. Prog.
(dollars in millions)

FY13
Approp.a

FY14
Approp.

FY15
Admn. Bdgt.

FY15 Hse. Bill H.R. 4800

FY15 Sen. Bill S. 2389

FY15 Final
H.R. 83

502 Single Fam. Direct
Self-Help setaside

$900
5

$900
5

$360
0

$1,042
5

$900
5

$900
5

502 Single Family Guar.

24,000

24,000

24,000

24,000

24,000

24,000

504 VLI Repair Loans

28

26.3

26.3

26.4

26.3

26.3

504 VLI Repair Grants

29.5

28.7

25

27

28.7

28.7

515 Rental Hsg. Direct Lns.

31.3

28.4

28.4

28.3

28.4

28.4

514 Farm Labor Hsg. Lns.

20.8

23.9

23.9

23.6

23.8

23.6

516 Farm Labor Hsg. Grts.

7.1

8.3

8.3

8.3

8.3

8.3

521 Rental Assistanceb

907.1

1,110

1,089

1,089

1,094

1,089

523 Self-Help TA

30

25

10

30

25

27.5

533 Hsg. Prsrv. Grants

3.6

3.5

0

0

3.5

3.5

538 Rental Hsg. Guar.

150

150

150

150

150

150

Rental Prsrv. Demo. (MPR)

17.8

20

20

20

20

17

542 Rural Hsg. Vouchers

10

12.6

8

8

8

7

Rural Cmnty. Dev’t Init.

6.1

6

0

5

6

4

a. Figures shown do not include 5% sequester or 2.5% across the board cut.
b. The final FY13 appropriation for RA included a $3 million 514/516 setaside; the final appropriations for FY14 and FY15 have no setasides.

HUD. The bill reduces funding for some HUD programs and provides level funding for others. Only Section 202 receives an increase. CDBG, HOME, rental assistance, and public housing have mostly small reductions below FY14 appropriated levels. SHOP, VASH vouchers for homeless veterans, Native American housing, AIDS housing, and lead hazard control all received the same levels as in 2014. The table below has details.

HUD Program
(dollars in millions)

FY13
Approp.a

FY14
Approp.

FY15
Admn. Bdgt.

FY15 Hse. Bill
H.R. 4745

FY15 Sen. Bill
S. 2438

FY15 Final
H.R. 83

Cmty. Devel. Fund
CDBG

3,308
2,948

3,100
3,030

2,870
2,800

3,060
3,000

3,090
3,020

3.066
3,000

HOME
SHOP setaside

1,000
b

1,000
b

950
10

700
10

950
b

900
b

Self-Help Homeownshp. (SHOP)

13.5

10

b

b

10

10

Tenant-Based Rental Asstnce.
VASH setaside

18,939.4
75

19,177.2
75

20,100
75

19,356
75

19,562
75

19,304
75

Project-Based Rental Asstnce.

9,339.7

9,516.6

9,346

9,346

9,346

9,330

Public Hsg. Capital Fund

1,886

1,875

1,925

1,775

1,900

1,875

Public Hsg. Operating Fund

4,262

4,400

4,600

4,400

4,475

4,440

Choice Neighbrhd. Initiative

120

90

120

0

90

80

Native Amer. Hsg. Block Grant

650

650

650

650

650

650

Homeless Assistance Grantsc

2,033

2,105

2,406.4

2,105

2,145

2,135

Hsg. Opps. for Persons w/ AIDS

334

330

332

303

330

330

202 Hsg. for Elderly

377

385.3

440

420

420

436

811 Hsg. for Disabled

165

126

160

135

135

135

Fair Housing

70.8

66

71

56

66

65.3

Healthy Homes & Lead Haz. Cntl.

120

110

120

70

110

110

Housing Counseling

45

45

60

45

49

47

a. Figures shown do not include 5% sequester.
b. In FY13 and FY14 SHOP was funded under the Self-Help & Assisted Homeownership Opportunity Program account. For FY15 the Administration’s budget proposed making the program a setaside in HOME. The final FY15 bill specifically rejects that proposal.
c. Includes the Rural Housing Stability Program, which is not yet operational.

HOUSE PASSES NAHASDA REAUTHORIZATION. H.R. 4329 would authorize housing programs for Native Americans and Native Hawaiians through FY18, but would limit funding each year to not more than the current $650 million level. The Senate bill (see HAC News, 8/6/14) does not cap funding.

NEW APPROPRIATIONS PANEL CHAIRS ANNOUNCED. For the new Congress convening in January, Rep. Harold Rogers (R-KY) continues in another term as chairman of the House Appropriations Committee. Rep. Robert Aderholt (R-AL) continues as chairman of the Subcommittee on Agriculture and Rural Development. Rep. Mario Diaz-Balart (R-FL) will be the new chairman of the Subcommittee on Transportation-HUD.

MENSAH SWORN IN AT USDA. On December 5, Lisa Mensah was sworn in by USDA Secretary Tom Vilsack as the new Under Secretary of Agriculture for Rural Development.

USDA ISSUES LIMITED ENGLISH PROFICIENCY GUIDANCE. The guidance is intended to help recipients of USDA funding ensure they do not discriminate against LEP persons. Contact Anna G. Stroman, USDA, 202-205-5953.

VA ADOPTS FINAL HISA PROGRAM REGULATION. The Home Improvements and Structural Alterations program serves disabled veterans. (See HAC News, 12/4/13.) Contact Shayla Mitchell, VA, 202-461-0366.

HUD EXTENDS DEADLINE FOR 202/811 COMMENTS. A notice in the December 11 Federal Register will move the deadline for comments on suggested regulatory changes (see HAC News, 10/17/14) to January 15. A HUD webinar about the proposal is posted online. Contact Alicia Anderson, HUD, 202-708-3000.

EMAIL LIST FOR USDA DIRECT SINGLE-FAMILY HOUSING LOAN PROGRAMS LAUNCHED. USDA will use the list to distribute information about Section 502 direct, 504, and 523. Sign up for this or for lists covering the Section 502 guarantee program at https://www.rdlist.sc.egov.usda.gov/listserv/mainservlet.

HAC HONORS RURAL HOUSING LEADERS. At the HAC Rural Housing Conference, Sen. Patrick Leahy (D-VT) and Rep. Harold Rogers (R-KY) received the Henry B. González Award for elected officials. The Clay Cochran/Art Collings Award for national service went to former Sen. Kit Bond. Recipients of the Skip Jason Award for community achievement were Brad Bishop, Self-Help Homes, UT; Martha Mendez, Coachella Valley Housing Coalition, CA; Retha Patton, Eastern Eight Community Development Corporation, TN; and Andres Saavedra, Rural LISC, DC.

HAC RURAL HOUSING CONFERENCE MATERIALS AVAILABLE. The conference app will remain active for at least six months, offering materials from each workshop, lists of attendees and speakers, and more. Videos of the plenary sessions, as well as photos taken throughout the event, will be posted soon. Check HAC’s website for updates.

RURAL VOICES COVERS POVERTY IN RURAL AMERICA. A special edition of HAC’s quarterly magazine asks what has changed since the War on Poverty was declared 50 years ago, what has not, and what can be done. Sign up online for email notices when new issues are published.

NEW HAC REPORT EXAMINES SENIOR HOUSING. Housing an Aging Rural America: Rural Seniors and Their Homes looks at the demographic characteristics of rural elders and considers ways to provide quality, affordable housing for them.

From a Spare Bedroom to a Home of Her Own

By Stacey Howard, Dream$aver IDA Program Director, NeighborWorks Umpqua

A Single Mother’s Struggle Out of Poverty to Provide a Better Life for Her Son

rv-se-2014-coverThis story appears in the 2014 Special Edition of Rural VoicesDouglas County, Oregon is arguably one of the most beautiful places anyone could hope to live. The icy cold waters of the North Umpqua rush headlong down from their headwaters at Lake Maidu in the Cascade Mountains. The North Umpqua crashes headlong into Little River at Glide forming the only head-to-head colliding rivers in North America. Tall evergreen forests give way to grass-covered, rocky hills of madrone and scrub oak. Outside Roseburg, the North and South Umpqua meet and join to make their way to the coast. Douglas County stretches from Central Oregon to the Oregon Coast and just a bit bigger than the state of Connecticut. For all the beauty surrounding the residents in Douglas County, life here can mean facing some ugly realities. Jobs are scarce. The median income is among the lowest in the state, and unemployment persists at higher levels than most of the state – and much higher than the national average. Resources, too, are limited by the rural nature of the county, and county budgets have been severely curtailed by the loss of timber revenues.

wfarmer

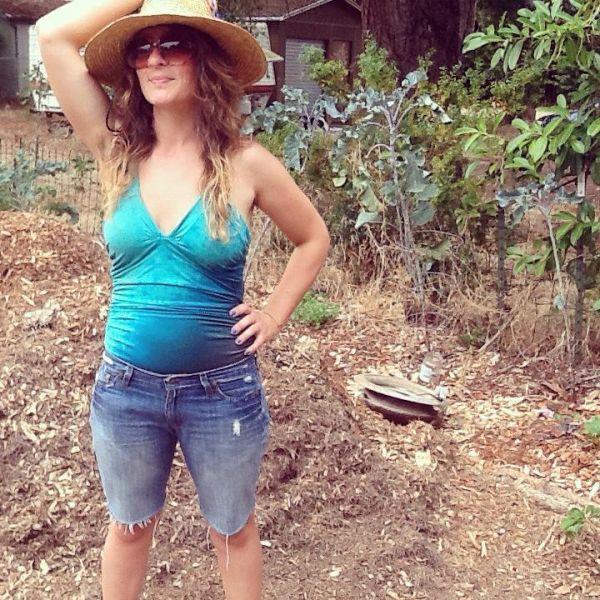
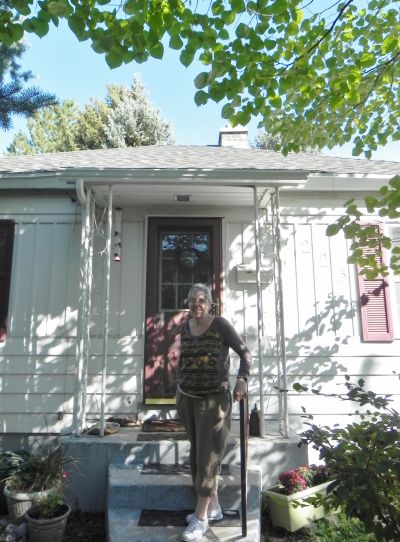
Chriset came to Roseburg (population about 21,000), the largest town in Douglas County, in 2011 with her 13 year old son, Gabe. Chriset was following her mother and sister who had moved to the area several years earlier. Driving into town in her dilapidated Toyota Camry, Chriset managed to find a temporary home for the two of them in the spare bedroom of a friend in tiny Sutherlin, 11 miles north of Roseburg.

Chriset came into town with no money, but a lead on a job at a Roseburg non-profit. She landed the job, and with her new salary – the most money Chriset had ever made – Chriset managed to rent a tiny one-bedroom attic apartment for her and Gabe. The apartment was freezing in winter and the baseboard heat was so expensive they rarely used it. Even with her new job, Chriset found the apartment difficult to afford. To conserve energy, Chriset would turn off her power at the main box every day before she left for work. With her new job, Chriset lost the food stamps that had been part of her food security. Chriset had no internet (and has never had cable TV), and made all of her meals at home from basic ingredients. Still, when Chriset’s car died after 3 months in Roseburg, she felt she could not afford a new one, and the old one didn’t seem worth repairing. Chriset says, “I can’t imagine how people can afford a car. I don’t have $200 extra in my budget each month!”

Chriset started bicycling to work, and Gabe (like most kids his age) was able to get around by bussing to school and walking or biking everywhere else. Chriset remembers their living situation was “sub-par”. After a few months at her new job, Chriset learned of a landlord who was willing to rent at a reduced rate to an employee at the non-profit where she works. Chriset applied for the rental, and she and Gabe moved into a spacious 3 bedroom historic house only a half a block from her job. To afford the new home, Chriset had to have a roommate, but she also had a garden, and Gabe had his own room. The new house, though roomier, was also old, drafty, and difficult to heat. Chriset wanted to quit moving around – she had moved so many times and twice had lost her rentals when the landlords went into foreclosure. Chriset wanted a home of her own.

In 2012, Chriset applied for an Individual Development Account (IDA) through another non-profit. The Oregon IDA Initiative provides a matched savings program for low-income individuals to help them purchase assets with the hope that they will become more financially stable and eventually move out of poverty. One of the eligible uses of the funds is the purchase of a first home. Chriset had to save $1000 of her own to receive $4000 in matching grant funds ($3000 from state funds and an additional $1000 from the federal Assets for Independence program). Chriset had savings accounts before but had never been able to build a balance. Through the IDA program, Chriset was saving money for the first time.

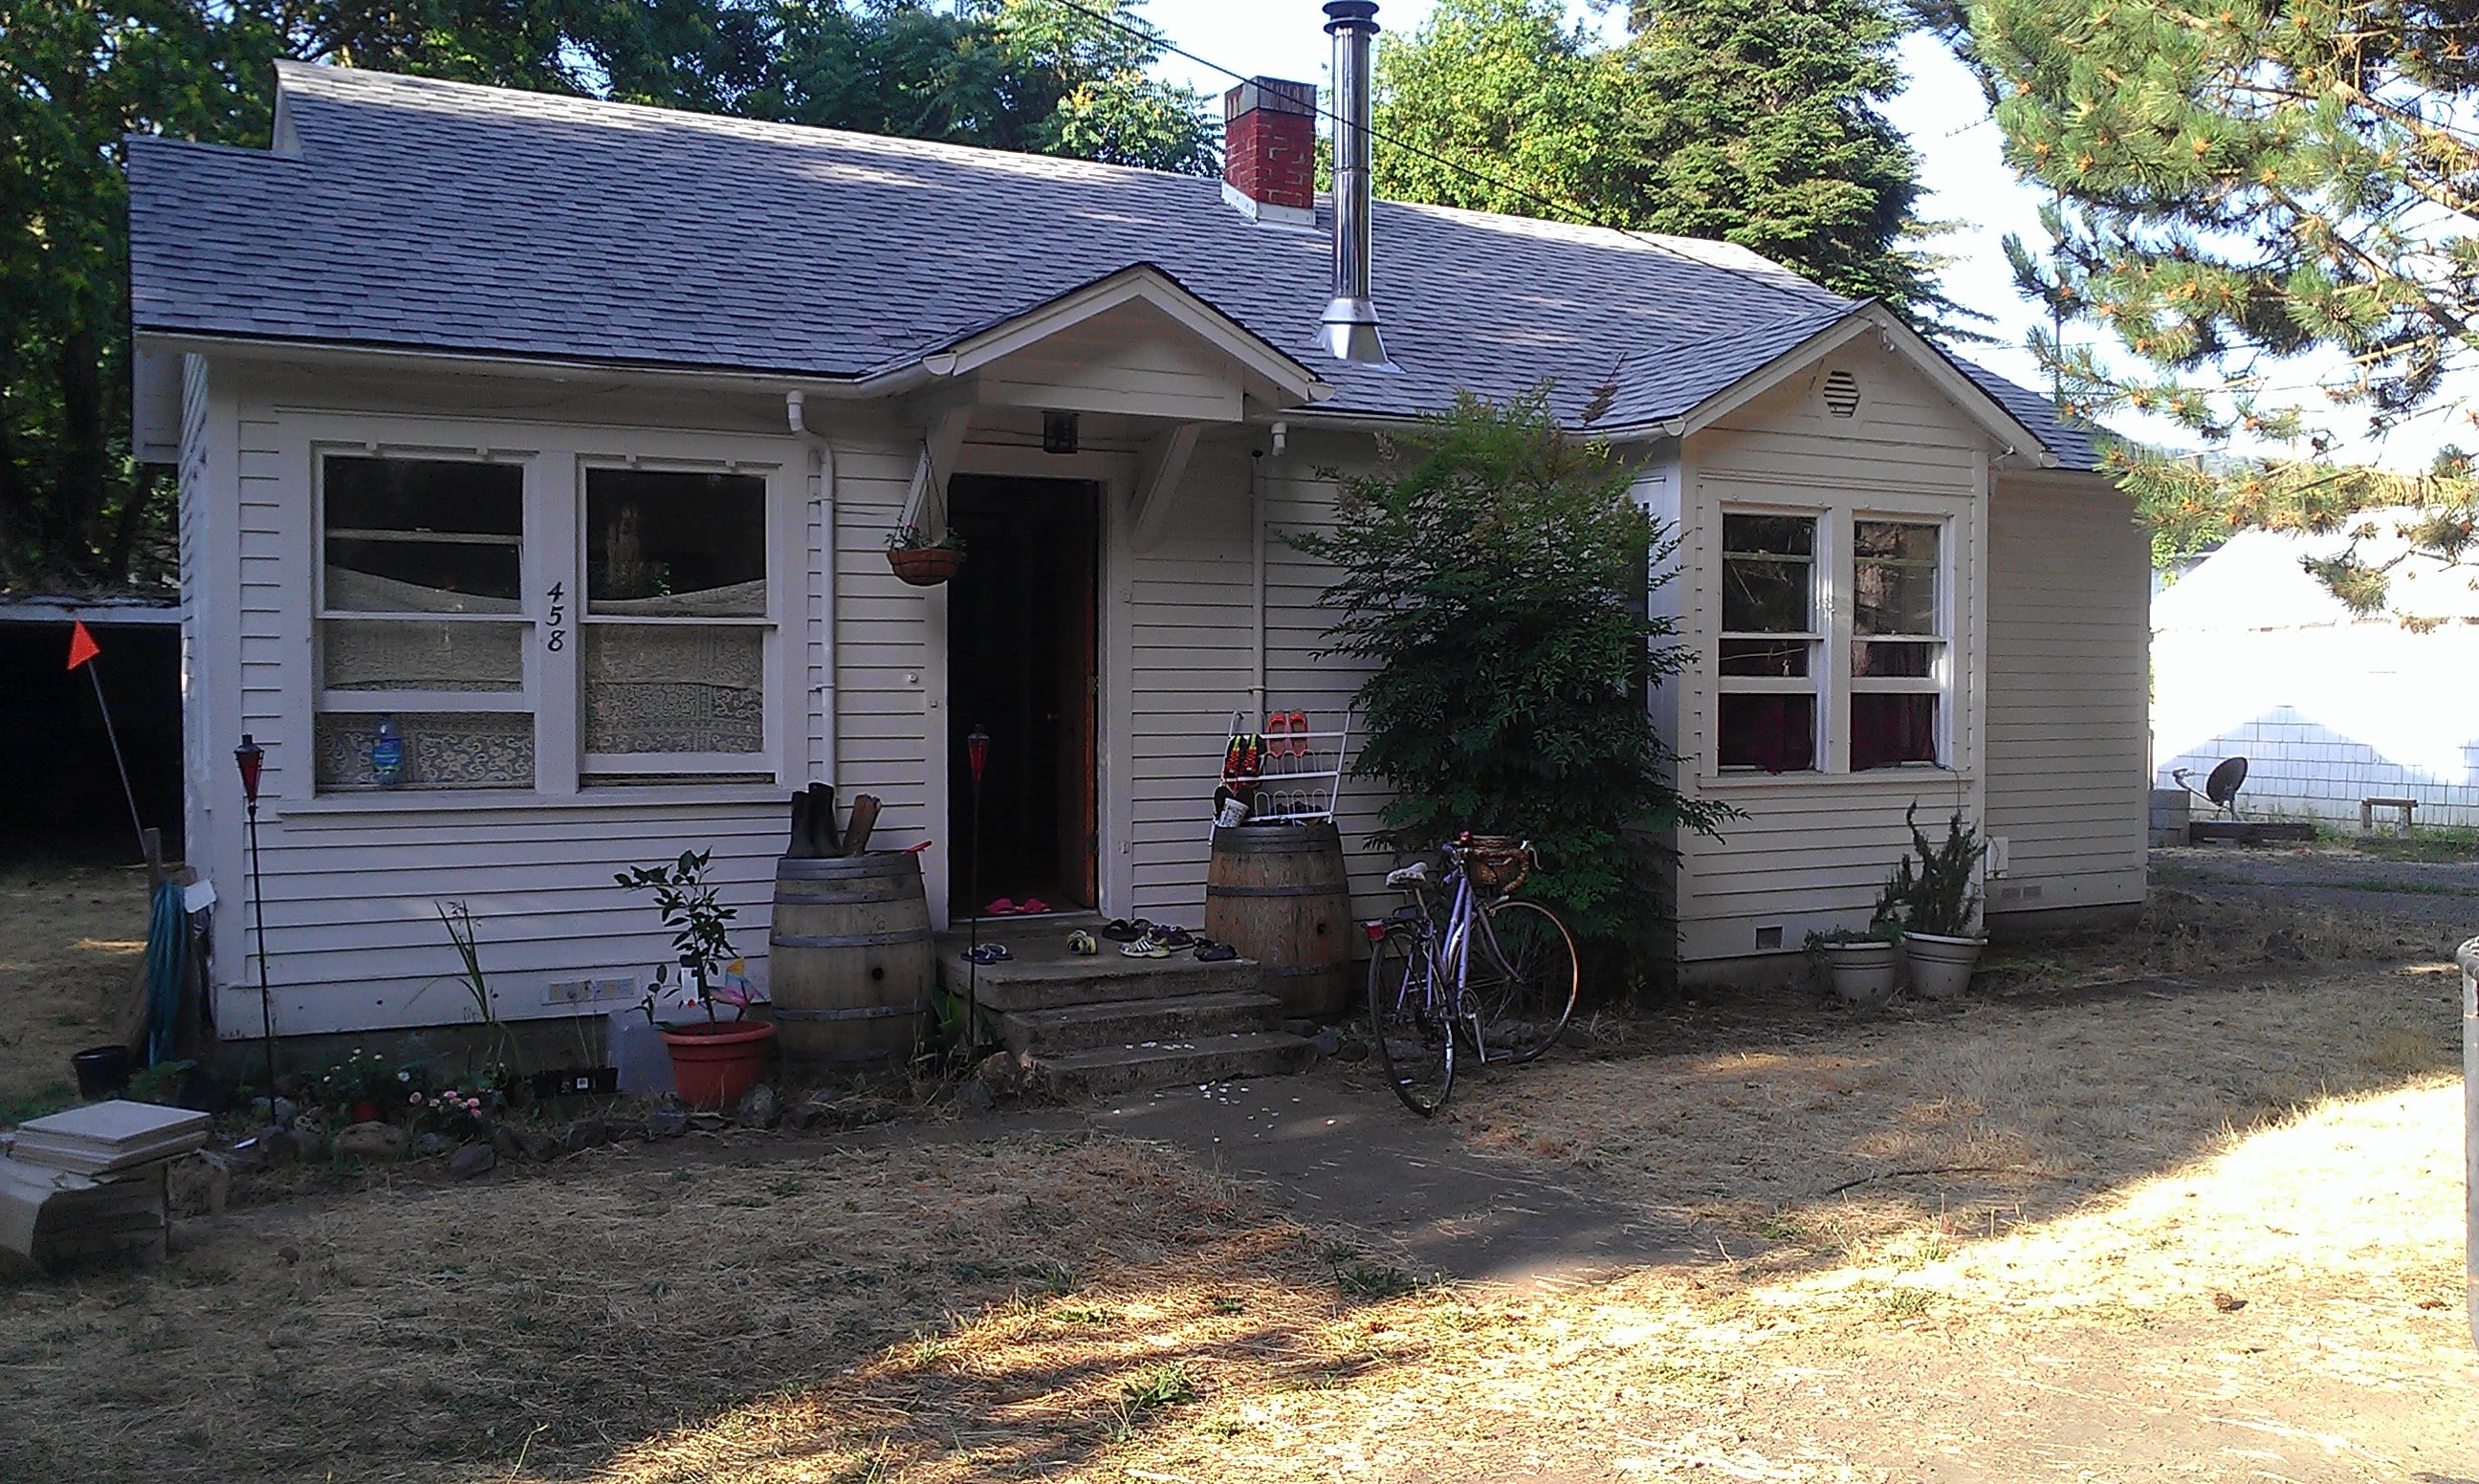
In addition to saving money, financial education helped Chriset improve her credit score and start tracking her expenses and budgeting using online resources. She also took home buying classes. Yet, Chriset was having a very difficult time finding anything suitable to purchase in her price range. She needed something close enough to her job and Gabe’s school that they could make do without a car. Chriset also needed a large yard with enough sun to continue growing her vegetables and fruits – and she wanted to be able to plant fruit trees. Chriset’s younger brother, a computer programmer in Seattle, offered to loan her additional money to make a deal work, and Chriset doggedly kept up her search. Finally, she found a property that was “distressed” – the current owner, an investor, needed to get rid of the property quickly because of cash flow problems. It met much of Chriset’s criteria; large lot, room for trees, two bedrooms, a big kitchen. A huge bonus for Chriset was a smaller cottage that she could rent out to help pay her mortgage. And, the price was right, at about $95,000. The house needed too much work to finance, but Chriset was able to convince the owner to carry a contract because of her ability to make a down payment.

whouse

In the late summer of 2013, Chriset and Gabe moved into their new home. Chriset immediately started a new IDA for some of the home repairs she would need. She shopped the local recycled building materials store for supplies, borrowed tools, and traded labor with friends. Chriset learned to replace windows, caulk, paint, and landscape. A whiz at bargaining, Chriset talked a local tree service into dumping wood chips in her yard for mulch. She planted fruit trees and her garden (with a few flowers for looks). She became a landlord and manages to pay half her monthly mortgage through the rental income. She has insulated, upgraded the electrical, and refinished her wood floors. While her home continues to be a “project house” – and she still is cold in the winter, at least until she saves enough for a new heating system – Chriset loves her home. “I get to paint my walls, and I don’t have to worry about having to move. I will have the mortgage paid off in 6 more years, and then I will start paying off my brother, but every month I know the money I am paying is going to benefit me in the future.”

Gabe walks 3 blocks to the local high school. Now entering his sophomore year, Gabe is earning A’s and B’s for the first time in his life. Says Chriset, “I don’t know for sure what is different now for Gabe…he’s a teenager, so you never know. But I am so thrilled with how he is doing.” Chriset and Gabe still eat at home, and their only modes of transportation are bicycles and their own two feet. Chriset says even if she had the money to buy a car, she probably wouldn’t until her student loans and loans for the house were paid off. Gabe gets insurance through the Oregon Health Plan, so Chriset doesn’t have to worry about his medical care, but just in case, she makes sure both of them stay healthy. Life hasn’t been easy for Chriset, but she says, “I like my life. Things have been rough, but they are getting better. Sometimes, if one more thing wasn’t totally OK…one little thing can devastate a family. Right now, I am happy.” Chriset’s face glows, probably from her healthy lifestyle of eating fresh, simple foods and bicycling many miles every week. But probably, it also glows because Chriset knows she has a home, one no one can take away.

Stacey Howard has lived and worked in rural Oregon for most of her life. She is currently the Director of the Dream$avers IDA Program at NeighborWorks Umpqua in Roseburg, Oregon.

Innovative Approaches to Improving Poverty Locally

rv-se-2014-coverThis story appears in the 2014 Special Edition of Rural VoicesThe problem of poverty is often viewed from a national or regional perspective. But success in moving people out of poverty can emanate from community-specific innovation and solutions.

MET, Inc. (Texas) | Pathstone (Puerto Rico) | NeighborWorks Umpqua (Oregon)

Job Skills through Housing Development

Based in Texas, Motivation, Education, Training, Inc. (MET Inc.) provides academic and vocational training to migrant and seasonal farmworkers. Although predominantly focused on serving farmworkers, MET Inc. also includes initiatives that target low-income and disadvantaged populations throughout the agency’s service area.

The colonias on the U.S.-Mexico border are one of the most impoverished regions in the United States. Located on the U.S.-Mexico border on the Rio Grande in Maverick County, Texas, the Rositas colonias are comprised of a cluster of numerous individual colonias all faced with the same substandard housing conditions and concerns. The housing stock in the Rositas colonias includes conventional stick-built structures, manufactured homes (that are often not hooked up to any infrastructure), adobe structures, and make-shift dwellings such as lean-tos.

MET Inc.’s housing staff worked to combine housing development and training for farmworkers. Faced with high unemployment rates, over one-third of the population in Maverick County has incomes below the poverty line. Through their housing program and their educational and vocational training programs, MET Inc. created an initiative that would rehabilitate homes in the Rositas colonias while providing construction training to the farmworkers living therein. MET Inc. secured an instructor through a partnership with Southwest Texas Community College, which had previously conducted a construction training program, and trainees were able to use the facilities at the college. MET Inc. initially received two rounds of Rural Housing and Economic Development (RHED) grants for the program. When RHED was discontinued, MET Inc. secured funding through HUD’s Rural Innovation Fund (RIF). Like RHED, RIF provides funding for capacity building for innovative rural housing and economic development activities.

Through leveraging funds, MET Inc. covers costs of tuition, buys tools for students, and pays a stipend to students while they are in the training program. Additional funding also came from the National Farmworker Job Program (NFJP), which provides job training and placement services to eligible farmworkers or dependents of an eligible farmworker who are in the country legally. The training program lasts for about 12 weeks and includes classroom and hands-on instruction. The initiative has seen success in meeting the basic housing needs of individuals in the Rositas colonias. Many families have hot water for the first time, children are able to have their own bedrooms as opposed to doubling up with parents or sleeping in communal spaces, and repaired homes are safer, more sanitary, and more secure than they were before.

The educational and vocational component has been extremely beneficial to those who underwent training. There is a need for people with construction skills in the region, and the program is helping provide this skill set to more workers securing higher-paying jobs and further increasing their quality of life. Through a combination of affordable housing provision, job training, and individual resilience, MET Inc. has created long-term and quality job options to the residents of the Rositas colonias.

Combating Poverty in Puerto Rico with Job Training & Economic Development

PathStone is a regional nonprofit housing provider that focuses on four major service areas: housing development, homeownership assistance programs, training and employment services, and economic development. PathStone has undertaken two innovative approaches to combating poverty in Puerto Rico in recent years – the Rural Innovation Fund economic development and agro-tourism initiative and the Pathways out of Poverty job training program.

Interested in integrating these various service areas to spur economic growth and development in a focused region in western Puerto Rico, PathStone requested and was awarded $2 million from HUD’s Rural Innovation Fund program.

The Rural Innovation Fund (RIF) is a comprehensive rural community economic development project in the Castañer Region of the western portion of the Island. In an effort to address the overall needs of this unique rural area, the approach combines the following elements into a single coordinated project to boost the local economy:

  • Training and employment services for workers;
  • Training and resources for farmers & growers;
  • Financial and technical assistance for micro enterprise and small business;
  • Collaboration with local organizations around the agro-tourism industry; and
  • Homeownership counseling and creation of affordable housing.

The target area is the center for coffee growing in Puerto Rico and there is a growing interest on the island in “agro-tourism” as well as organic farming. There is a local desire to attract tourists from on and off the Island into the mountain region to discover the process of coffee production while enjoying the natural beauty of the area.

The focus for economic development is the Route 123 corridor, a route traditionally used to bring goods from the rural mountainous areas to market in Ponce. The RIF program boosts the agricultural sector, especially coffee, and hospitality and tourism industries and increases the number of job opportunities for low income workers, as well as supporting small businesses and micro enterprises linked to agro-tourism.

PathStone leads the initiative in partnership with the School of Architecture of the Pontifical Catholic University of Puerto Rico, the Tourism Company of Puerto Rico, Massachusetts Institute of Technology (MIT), the Center for the New Economy (CNE), the Conservation Trust of Puerto Rico, and the Small Business Administration (SBA).

One of the entrepreneurs assisted is Miriam Sierra, owner of the Restaurant Alborada, located in Castañer. Sierra received technical assistance and funding from PathStone to expand a local cafeteria into a full bakery that now sells a wide range of pastries and baked goods.

To promote the launch of the new corridor, PathStone, in collaboration with the School of Architecture, developed the bilingual tourist magazine “Route 123: More than a Route, It’s a Culture.” The publication details the various attractions, resources, and businesses along with corridor between Ponce and Utuado. It also describes in both words and beautiful photos the history, culture, food, and geography of this unique area.

To date, the PathStone RIF program has provided technical assistance to 139 entrepreneurs and small businesses and has created or retained 110 jobs. The PathStone Enterprise Center (our CDFI affiliate) has also originated 5 small business loans.

In addition to the RIF program, PathStone also received a Pathways Out of Poverty grant from the US Dept. of Labor to provide green jobs training to residents in high poverty areas who are unemployed, have been incarcerated, or lack a high school diploma. This “Green for Gold” program targeted three areas; Rochester, NY, Scranton, PA, and portions of Puerto Rico.

The rural areas of Puerto Rico targeted by this program have poverty rates of over 50 percent and unemployment in the 18-21 percent range. Through Pathways out of Poverty, 1,158 individuals completed training courses and 554 participants secured in full time, unsubsidized employment. 356 of these individuals obtained jobs directly related to the training they completed. PathStone also assisted close to 300 individuals in attaining their high school equivalency, further positioning them for future career growth.

Both the Rural Innovation Fund and Green for Gold have proven to be effective models for combating pervasive poverty and helping families work toward a more secure future.

IDAs Help Low-Income Families Save for Increased Opportunities in Rural Oregon

In rural Oregon, where jobs are scarce, options for employment may seem limited. Funds to start a business of your own may be practically impossible to find. However, thanks to an innovative tax credit program called the Oregon Individual Development Account Initiative (ORIDA), currently funded at 10 million dollars per year, Oregon residents earning as much as 80 percent of statewide median income can qualify for up to $9,000 to help start a business, get post-secondary training or education or “assistive technology for employment” to help them get back on their feet. NeighborWorks Umpqua Dream$avers IDA program currently serves over 1,000 participants and is working to build businesses, homes, and affordable housing as well as help government and other agencies to provide needed infrastructure, conserve resources, and develop a stable local economy.

The Dream$avers program allows participants to save up to $3,000 over a period of up to 3 years. The savings are then matched, typically at 3:1. Eligible uses, in addition to those mentioned above, include the purchase of a home for first-time homebuyers, and home repairs, maintenance, or modifications to increase accessibility for disabled homeowners.

Participation in Dream$avers requires participants to actively partner and work toward their financial goals. All participants complete 16 hours of financial and asset-specific education. Statewide, approximately 4,000 savers work individually with an IDA Specialist to reach their goals. Savers must deposit into their IDA monthly, in amounts that will allow them to reach their goal savings.

IDA savers, even those who don’t complete the program, report higher levels of economic satisfaction with their lives, increased use of budgets, and increased use of savings accounts.Participants appreciate the financial boost that comes from being able to accelerate the impact of their savings through the program match. IDAs reduce student loan debt load after college, capitalize microenterprise, increase home equity at the time of purchase, preserve the asset of home ownership by allowing for repairs that preserve the home, and help people get better jobs with assistive technology. IDA funds are paid directly to the vender for the asset being purchased, so there is no tax owed on the benefit by the participant.

Oregon advocates for the ORIDA program are always working to innovatively improve the IDA program, and the demand for accounts currently outstrips our capacity to serve new participants. As we advocate in 2015 for the renewal of the tax credit that supports this innovative program, the future will continue to present challenges and opportunities. For now, this program is a resounding success for Oregonians.

HAC would like to thank M.E.T. Inc., PathStone, and NeighWorks Umpqua for their contriutions to this edition of Rural Voices and their tireless work improving the lives of low-income families within their communities through traditional and innovative methods.

"The People Left Behind" Are Today the People Still Behind

By Joe Belden and Lance George, Housing Assistance Council

rv-se-2014-coverThis story appears in the 2014 Special Edition of Rural VoicesThe United States has a long – but not recent – history of important, high-level efforts to combat rural poverty. The Homestead Act of 1862, Theodore Roosevelt’s 1909 Country Life Commission, and the Resettlement and Farm Security Administrations during the New Deal were such efforts, strongly supported by Presidents. Very recently, there has been wide recognition of the 50th anniversary of Lyndon Johnson’s war on poverty and the Economic Opportunity Act of 1964. Less well known was another effort that began in 1966: President Johnson’s creation of a National Advisory Commission on Rural Poverty. It held hearings, conducted research, and in September 1967 produced a 160-page report, “The People Left Behind,” that is still relevant today. The report’s summary begins: “This is a report about a problem which many in the United States do not realize exists. The problem is rural poverty. It affects 14 million Americans. Rural poverty is so widespread, and so acute, as to be national disgrace…. The total number of rural poor would be even larger than 14 million had not so many of them moved to the city…. This Nation has been largely oblivious to these … impoverished people left behind in rural America.”

The report found that the rural poor population is characterized by low incomes, higher unemployment, low educational attainment, poor housing, hunger, malnutrition, and a higher infant mortality rate than among the least privileged urban groups. The Commission also laid out several primary recommendations to “eliminate” poverty in rural America:

  1. The U.S. should adopt and effect a policy of equal opportunity for all people,
  2. The national policy of full employment, inaugurated in 1946, should be made effective,
  3. Our federal government should assure all people enough income for a decent living,
  4. Manpower policies and programs should be revamped,
  5. Rural education should be improved,
  6. Better health services with family planning should be provided,
  7. An improvement should be made in rural housing, and
  8. Multicounty districts should be formed to plan cooperatively and coordinate programs for economic development.

The report also recognized that rural is more than agriculture. The impetus and energy behind this focus on rural poverty coincided with several large-scale and better-known policy and government initiatives to combat poverty and inequality more generally. These included the Social Security Act of 1965 (Medicare & Medicaid), the Food Stamp Act of 1964, the Elementary and Secondary Education Act, the Office of Economic Opportunity, VISTA, the Community Action Program, Job Corps, Head Start, Legal Services, the Appalachian Regional Commission, and the continuation and expansion of many New Deal initiatives.

A commitment to the improvement of housing conditions among the rural poor was also evident in dramatic increases in USDA’s housing production through the Farmers Home Administration (FmHA). FmHA’s housing programs began in 1950, but were not expanded and widely used until the 1970s. Between 1970 and 1980, over 1 million low-income rural households became homeowners through low cost mortgage loans from FmHA. In fact, roughly one-half of all direct homeownership loans ever issued by USDA were made in the 1970s alone. Similarly, more than 40 percent of affordable rental housing units funded by USDA were developed between 1963 and 1980. Additional housing improvements and efforts were initiated by the newly formed U.S.

Department of Housing and Urban Development (HUD) throughout rural America during this time. The pace of anti-poverty efforts slowed markedly in the 1980s after substantial cuts in domestic federal aid and social safety net programs. In the mid-1990s, the Personal Responsibility and Work Opportunity Act of 1996, or “welfare reform,” was enacted. While welfare reform was largely viewed as a success in moving people to work, the overall impacts are still being assessed and can vary widely by state.

Today, poverty, and especially rural poverty, seems to have become an afterthought in national priority or action. “Inequality” is the more politically correct word. But more than 40 million Americans – one-quarter of whom live in rural communities – still have incomes below the poverty threshold. The poverty rate has been consistently higher in rural America since the government began keeping track of this condition in the 1960s. There has been no increase in the federal minimum wage in five years. And in the recent severe recession, many Americans slipped into poverty and lost their jobs, homes, or both.

Increased access to health insurance through the Affordable Care Act is a significant accomplishment for low-income people. But new or meaningful federal actions to improve the economic and living standards of our poorest citizens are sparse to nonexistent. While progress in the long fight on poverty is undeniable, it could be argued that much of that success was a direct result of the energy and effort of the substantial federal investment in the early years of the war on poverty.

In a 1966 message creating the Commission on Rural Poverty, President Johnson wrote that “[t]he abolition [of] rural poverty may require a journey of a thousand miles.” “The People Left Behind” found that there were 14 million rural Americans living in poverty. We have come some of the way. But in 2014 10 million rural people are still “left behind.” Isn’t it time that the federal government and its leaders once again pay attention to the stain and injustice of poverty and help the millions of rural Americans who are still behind?


Decline in Senior Poverty: A Success Story….

By the Housing Assistance Council

rv-se-2014-coverThis story appears in the 2014 Special Edition of Rural VoicesOne of the biggest successes in reducing poverty has been among older Americans. Until recent decades, elderly persons in the United States experienced poverty rates at much higher levels than the overall population. The enactment of safety net programs such as Social Security, Supplemental Security Income (SSI), and Medicare have likely contributed to the reduction in the poverty rate of seniors over the past half century. In the mid-1960s, nearly 30 percent of seniors in the United States were in poverty – this has steadly declined to 9.5 percent by 2013.

While these reductions in older age poverty are significant, these reductions have not occurred evenly across the board. Rural seniors experience higher poverty than seniors nationwide, at 11.4 percent, and older women have higher poverty rates than their male counterparts. Overall, 14 percent of rural elderly women have below poverty-level incomes, compared to 8 percent of rural men over the age of 65. Senior minorities in rural areas are among the poorest and worst housed groups in the entire nation. While just 10.8 percent of all elderly households in rural America are headed by minorities, they account for 22.9 percent of all rural elderly households in poverty. In comparison, 9.12 percent of all rural white, non-Hispanic individuals fall below the poverty line. Additionally, while poverty rates for seniors are now lower than the overall population, the looming demographic shift of baby boomers progressing into older age may present challenges that halt, or even reverse, this progress.

…With a Cautionary Outlook

…With a Cautionary Outlook

By Kim Datwyler, Executive Director, Neighborhood Nonprofit Housing Corporation (NNHC)

Staying Housed on a Fixed Income: The Importance of Available Affordable Housing for Seniors

rv-se-2014-coverThis story appears in the 2014 Special Edition of Rural VoicesDuring the past decade, the overall poverty rate for Americans age 65 and older has held steady at about 10 percent. However, examining this data reveals significantly higher rates of poverty among older women and minorities. Single females 65 and older represent approximately 70 percent of people over 65 living alone; many have not spent as much time in the workforce as their male cohorts, nor did they have similar earning power. Many rely on SSI, which can place them in vulnerable financial positions. This is not a problem faced solely by senior women; several of the Neighborhood Nonprofit Housing Corporation’s (NNHC’s) rental property managers have noted that there is a growing trend of tenants whose only source of income is SSI. Corroboratively, the AARP states that “among all older Americans in 2012, almost half relied on Social Security for 50 percent or more of their family income, while nearly one in four relied on Social Security for 90 percent or more of their family income.” This leads to many seniors living from one SSI check to the next, with little or no contingency for emergencies. In recent years, NNHC’s property managers have also seen an increase in the number of tenants using local food pantries; these data is supported by the findings of a 2013 National Foundation to End Senior Hunger study. “In 2011, almost one in every 12 seniors above the age of 60 in the United States was food insecure. That represents 4.8 million seniors nationwide, which is more than double the number of food insecure seniors in 2001.”

Tenants who live near a food pantry that provides free deliveries are particularly fortunate. A recent survey of senior properties in Utah found that over half of seniors do not own a vehicle. They rely on public transportation, which can be limited or even nonexistent in rural areas. An NNHC tenant who has lived in both large urban centers and small rural areas noted that rural areas tend to be less pedestrian friendly, lacking wheelchair-friendly curbs and even sidewalks. One rural senior noted that without public transportation, getting to medical appointments becomes very difficult. Consequently, she felt rural seniors were less likely to get the health care they needed.

River Park residents

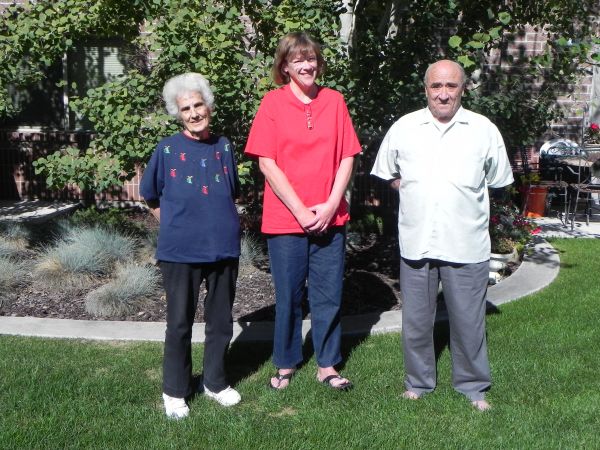
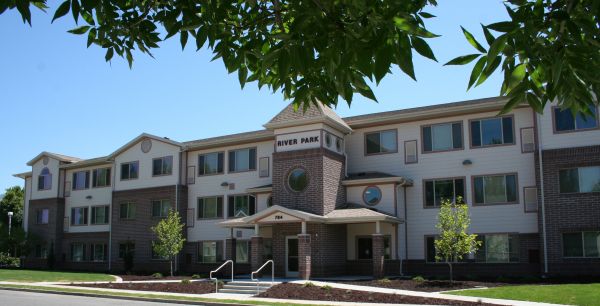
These challenges faced by seniors are only too familiar to Deanne Jones, a resident at NNHC’s River Park Senior Housing property in Logan, Utah. Deanne was employed and renting a small home when she faced a permanent disability and eventually had to stop working. She went from being able to provide for herself to having to choose between paying for rent or buying groceries. After several months of difficult financial struggles, she read an article in the local paper about a new affordable senior property that was under construction. She called immediately and put her name on the list to be contacted when a unit became available. She called frequently to check on the progress of the development and was one of the first tenants to move in. She counts her current apartment as a “huge blessing” and is grateful to have both a roof over her head and food on the table as well as neighbors that help watch over one another. Deanne expressed appreciation to both the LIHTC and HOME programs for funding the River Park property that gave her the ability to be independent and maintain her dignity. To her, these programs are “critical” and a lifeline to seniors in need.

RP1

Another resident, Larrie Lou Hogge, has lived in River Park for just over two years and says she “loves it!” She admits that living solely on SSI is difficult, even with the affordable rent she pays. Increased food and prescription medicine costs have stretched her budget, but she is happy to have a home with a community feeling. The local Independent Living Center provides her invaluable support via a weekly shopping trip; as a wheelchair user, it is difficult for her to get around. Without some form of public transportation, she would lose the ability to live independently.

Senior homeowners also struggle to make ends meet. Regina Clements lives in a home that is as old as she is – a spry 75. Unfortunately, the home wasn’t doing as well as its owner; the chimney was falling apart, the roof needed repairs, and the home only had a few rain gutters and no downspouts. When it rained, Regina could stand at the window and watch pieces of shingles fall off the roof. In the winter, she had six foot icicles hanging from her eaves. Regina didn’t have the funds to make much-needed repairs, but then she read in her city utility bill about a home rehabilitation program that offered grant funds for homeowners in her situation. At first, she felt it was “too good to be true,” but still attended the orientation meeting. She found most of the other attendees were in similar situations; they owned older homes that needed repairs and simply didn’t have the ability to pay for them. The Northern Utah Neighborhood Improvement program provided Regina with a $9,800 grant to remove the chimney, replace the roof, and install rain gutters with downspouts. The program requires its participants to “give back” through community service, and Regina was tasked with organizing a neighborhood cleanup. Now her neighbors will benefit from her efforts, and she has enjoyed interacting with people from all walks of life. She sees this as a “wonderful program that should be continued” and one that acts as a catalyst to make other good things happen. But future program funding is always tentative; previous support has come from CDBG, the Federal Home Loan Bank of Seattle, and affordable housing money from partnering cities.

Regina and home

There is a need for affordable housing for seniors throughout the country. U.S. Census data shows very clearly that people are living longer; it is forecast that the proportion of people age 65 and older will grow from 12.5 percent in 1990 to 17.7 percent in 2020, a 41.6 percent increase. By the year 2060, the number of people age 65 and over is expected to top 92 million. Extended funding cuts to federal housing programs, as well as HOME and CDBG funding, have made it harder to provide affordable housing programs for very low-income seniors, particularly in rural areas. Smaller rural populations equate to smaller projects which do not allow for developmental economies of scale like those of larger urban projects. In addition, rural communities have fewer resources to contribute to affordable housing projects than their urban counterparts.

Safe, affordable housing is a crucial need for our nation’s seniors, and providing them opportunities to remain independent is not only better for them, but it also makes economic sense for everyone. It is up to us to make certain our nation’s policy makers understand and support this premise. After all, isn’t everyone aging?

– Kim Datwyler has been the Executive Director of the Neighborhood Nonprofit Housing Corporation (NNHC) since 2000. Founded in 1996 with a mission to create affordable housing opportunities, strengthen and enhance communities, and provide households with the skills to become self-sufficient; NNHC’s primary focus is to assist underserved communities, particularly in Utah’s rural areas.

A Frank Discussion on Persistent Poverty in Rural America

rv-se-2014-coverThis story appears in the 2014 Special Edition of Rural Voices Forgotten or hidden from mainstream America, several rural areas and populations are isolated geographically, lack resources and economic opportunities, and have suffered through decades of disinvestment and double-digit poverty rates. Persistent poverty is most evident within several rural regions and populations, including the Lower Mississippi Delta, the rural Southeast, Central Appalachia, Native American lands, the colonias along the U.S. Mexico border, and migrant and seasonal farmworkers.

Among the most economically depressed areas in the country, addressing social, economic, and housing problems has proved challenging. To help better understand this issue, Rural Voices spoke with five housing experts, each with decades of experience providing housing and working with low-income families in persistent poverty areas. Their firsthand knowledge presents an unparalleled view into the harsh reality of families and communities grappling with long-term poverty. These experts offer their insights, passion, and commitment to help solve what is often considered an intractable problem.

What does poverty look like in your community or region?

Ann Cass: In Hidalgo County, Texas, one out of every three people in our community is poor. One out of every two children is poor. This poverty is lived out in the Rio Grande Valley of Texas, a region that has no viable public housing program. This means that, typically—usually—a child will be living in a neighborhood or colonia that looks like a shanty town in a third world country.

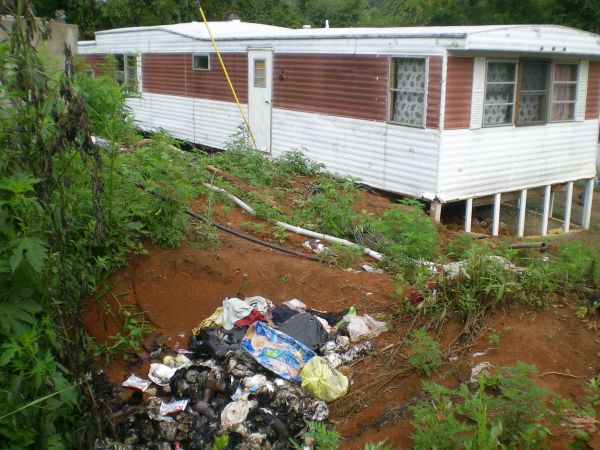
The families live in mobile homes with busted walls and ceilings, in shacks made of grocery store pallets or in sheds made out of old political campaign billboards. If you visit such a home, you will find two or even three families living in the same home.

Selvin MaGahee: I’m located in rural central Florida, and I work in rural communities throughout the Southeastern United States and Puerto Rico. There are many places in these areas that define persistent poverty. It looks like remnants of the economic and educational inequalities that have persisted since the post slavery/Jim Crow era throughout much of the rural south. There are still many racially segregated neighborhoods that contain a disproportionate share of substandard housing and other examples of economic hardship.

Half the students who begin kindergarten will not graduate from high school. In the midst of their long suffering I see resilience, persistence, creativity, and strength. I see a people who need hope.
-Ann Cass

Bill Bynum: Nationwide, one out of four persistently poor counties and parishes are located within the Mid South states. In Louisiana and Mississippi, over half of the states’ counties and parishes are classified as persistently poor. Within these counties and parishes, poverty and race are inextricably connected. Thirty-five of the region’s thirty-nine counties and parishes in which the African American population exceeds 50 percent have had poverty rates in excess of 20 percent consistently for the last three decades.

Tom Carew: One thing you can surely say about poverty in Central Appalachia: it is persistent. Since the War on Poverty began in the 1960s, Central Appalachia has remained at the bottom. That is not to say there has been no progress over the past 50 years. There is much to celebrate: safe drinking water, sanitary sewers, four lane highways, hospitals, good schools, the incidence of homes without full plumbing, a prime indicator of substandard housing, are at historically low levels.

Unfortunately even with all the improvements the region remains at the bottom compared to the rest of the country. In Central Appalachia, especially the coal fields, unemployment has increased as the demand for coal has decreased primarily due to the price of Natural Gas and Environmental concerns. It is very difficult to find replacement employers who can pay annual salaries of $60,000.
Collins Week five 10

Ann Cass: If I were to sit at a table and visit with the head of the household in the colonias in Hidalgo County, the conversation would be terse, for these are people who work long hours for little pay and less relief, and many hold down two or three jobs at minimum wage. The conversation may well be guarded, for many of these families are of mixed-immigration status, and there is no telling when a beloved uncle or cousin will be picked up and “disappeared”—deported back to Mexico.

The children are children, and play and laugh and are affectionate. Yet, the educational system fails so many. Half the students who begin kindergarten will not graduate from high school. In the midst of their long suffering I see resilience, persistence, creativity, and strength. I see a people who need hope. As we attempt to offer them that hope, somehow we are gifted with hope by them.

Pinky Clifford: Here, on the Pine Ridge Reservation, poverty looks like the word “without.” The vastness of our area captivates visitors but it doesn’t take long for them to experience just how large it is out here. My thirty-five mile commute to work (one way) consists of two stop signs and two traffic lights (my driveway doesn’t count). When I say that poverty looks like the word “without” it means we do without adequate housing, jobs, health care, economic development, and improved road systems. In our area poverty looks like older trailers and manufactured homes in desperate need of repair or replacement. Poverty looks like the many roofs, windows, and doors that need replacement and severely overcrowded homes. Poverty makes us look like we don’t want to work or do anything for ourselves, and at the same time, poverty masks the positive in the community.

While the causes of poverty are complex and varied, what do you feel are a few of the biggest contributors in creating the long-term poverty that exists within your community or region?
discussion-authorsTom Carew: It is the economy of Central Appalachia that drives poverty. The outflow of our young people to the urban centers is primarily driven by the job market. While our political and economic development leaders work hard to attract industry to Rural Appalachia, it is an uphill battle. Some folks from my hometown of Morehead, Kentucky drive over 140 miles per day to jobs in Lexington or Georgetown, Kentucky.

Recruiting teachers to McDowell County is difficult, and even if they are recruited, affordable housing for young teachers is not available.
-Tom Carew

The four lane roads have helped make this possible, but isolation is still evident in towns like Welch, WV, a two hour drive to the nearest four lane highway. As the 2013 school year began in McDowell County, WV, they were 50 teachers short! Due to its isolation, recruiting teachers to McDowell County is difficult, and even if they are recruited, affordable housing for young teachers is not available.

Pinky Clifford: I think our economic corridors have limited growth and access to landowners so that they are unable to live on their own land. We constantly go elsewhere to purchase goods and services that could be provided right here to create jobs, financial stability, economic development, larger schools, adequate health care, and safe communities. One of the biggest contributors in dealing with long-term poverty is the huge growth spurt that we’ve had. Over 50 percent of our population is under the age of eighteen. We have never had a lot of economic opportunity offered to us until the last twenty-five years or so.

Bill Bynum: One of the biggest contributors to long-term poverty includes a systemic lack of access to opportunity structures for the children and families that live in economically distressed communities. Poor communities are less likely to have high quality schools and access to good jobs than communities of affluence.

Selvin MaGahee For many of the unskilled and/or uneducated workers in my area, the minimum wage does not afford them a fair opportunity to take care of themselves and their families, even when working two jobs. Furthermore, some are locked out of the job market because of criminal records, often for petty offences that receive unequal treatment in the judicial system based on race or ethnicity.

Ann Cass: One of the biggest contributors to long-term poverty is companies paying poverty wages rather than a living wage. The low wages mean that our talented craftsmen often migrate north where they can make three or four times that amount but at the cost of leaving their families and community behind. With low-wages people also succumb to pay day loans and title loans, which keep them in economic bondage.

Bill Bynum: The relationship with a depository financial institution matters greatly. Low-income families with an account at a depository are more likely to own assets than families of similar means without an account. Additionally, in low-income neighborhoods, there is a strong relationship between the presence of a branch and the origination/cost of mortgages. Responsible financial institutions provide families with the tools needed to accumulate assets that pave the way for families to get ahead. In communities mired in the cycle of long term poverty, the presence of sustainable, responsible financial institutions is often absent relegating services to instead be provided by high cost, wealth stripping entities.

Tom Carew: In Central Appalachia, low-wages make it near impossible to access traditional financial markets because of strict underwriting.

Ann Cass: Our cities refuse to provide affordable housing, even though they want low-income people to maintain their golf courses, clean municipal buildings, work in restaurants and hotels. In Hidalgo County, working families have no other choice than to live in a rural colonia (shantytown). There is no planning and zoning enforcement in the unincorporated areas of the county where most of the 1,200 colonias are. This means no garbage collection, street lights, parks and recreational areas. There is no building code enforcement. Public transportation is practically non-existent, health care is perceived as a privilege, not a right, and people die of diseases that in this country they should not die of. Because poverty has existed here for so long, in a racist system where people of color do not have access to resources, decision making, or leadership, many have developed a learned helplessness of “this is the way it has been, is, and will be forever.”

How much can a home take with such severe overcrowding?
-Pinky Clifford

Pinky Clifford: In all my years on this planet, I have seen and heard about economic initiatives that have come and gone doing little to address the long-term poverty.

With your experience working in these regions, what are some of the changes you have seen in the nature and level of poverty over the past few decades?

Pinky Clifford: Conditions are worse on Pine Ridge. With a larger population and not many more jobs, homes or rentals, and more quick fix trailers, you have more wear-and-tear on everything: stress on families (substance abuse, suicide, domestic violence), road systems, hospitals, schools, homes – how much can a home take with such severe overcrowding? When everything becomes worn you think of replacement, and when you don’t have the resources for replacement, then the community degenerates and the veil settles in.

Ann Cass: The colonias now have some infrastructure; paved streets, potable water, either public sewer or septic fields, but they still need street lights, parks, garbage collection, and drainage systems. After Hurricane Dolly, we were building in 10 colonias that were under water for more than 120 days!

Although finding a decent paying job in the area is still a challenge, more and more children from the colonias are going on to college. School districts are beginning to replace ESL classes with dual language enrollment, teaching classes in English and Spanish from k-12 grades. These schools are graduating students who are fluent in both languages.

Selvin MaGahee Over the past few decades I have seen many substantial changes for the better. Most of the flagrant acts of racism and discrimination, often supported by public institutions, have gone away. Laws have been enacted that make such acts illegal, although in many cases, acts of discrimination have become more subtle and much more sophisticated. This has been evident in the past couple of years through the dismantling of some of the long established protections including voting rights, government contracting, educational opportunities, and so on.

Tom Carew: Life without question is better in the physical sense. Water, sewer, hospitals, health care, highways, school facilities, and reasonably priced utilities are all much better than they were 50 years ago. On the other hand, high school dropout rates remain high in many counties, and persistent unemployment and low-paying jobs can be seen throughout the region. Unemployment in the coal fields is high.

Despite robust profitability, bank branches have closed at high levels –disproportionately in high poverty areas.
-Bill Bynum

Are we better off than 50 years ago? Most definitely – but as we look at Central Appalachia as a region, we remain at the bottom when compared to the rest of these great United States.

Bill Bynum: One phenomenon on which we have been paying close attention is the proliferation of bank deserts. Despite robust profitability, bank branches have closed at high levels –disproportionately in high poverty areas. In Mississippi alone, 1,031 of 1,679 ZIP codes are bank deserts.

When banks decide to leave certain markets, particularly markets with a substantial population of low-income residents, leaders face a continuum of choices. At one end, banks can work to find responsible, sustainable alternatives through partnerships with Community Development Financial Institutions (CDFI) and nonprofit organizations. At the other end, banks can simply export the community assets held in the branches slated to close to more affluent communities without consideration of the residents left behind. We’ve seen both approaches applied by banks – it remains to be seen whether or not the financial sector in our region can embrace a habit of meaningful collaboration.

What are the ramifications of persistent poverty for affordable housing provision within your community?

Bill Bynum: Within the Mid South’s persistently impoverished communities, and particularly those with high populations of African Americans, high cost lending was particularly prevalent during the early part of the last decade. Mississippi provides a good case study. In 2007, black households in Mississippi received approximately 10,000 mortgages. Four out of 10 mortgages to black households in Mississippi were classified as high cost loans. The same year, white Mississippi households received 36,000 mortgages, of which 2 out of 10 were classified as high cost.

A disproportionate amount of substandard housing is located in low-income communities
-Selvin McGahee

In 2012, mortgage originations for black households were just over half the number of mortgages originated in 2007. High cost lending dropped drastically; however, prime loan lending to African American households remained significantly below 2007 levels. For white households, high cost lending also dropped, however the drop had been more than made up for by increased levels of prime lending with both prime and total mortgage originations surpassing 2007 levels.

Selvin MaGahee Persistent poverty makes it very difficult for people in the rural south to improve their living conditions. A disproportionate amount of substandard housing is located in low-income communities. The economic downturn that began 6-8 years ago has made fewer resources available and decreased the availability of affordable housing. Housing policies at the federal, state and local levels have also had a negative impact on affordable housing. Things are not getting better; in fact they are getting worse.

Tom Carew: Central Appalachia has its urban centers: Morgantown, Charleston, Knoxville, Kingsport, Johnson City, Bristol, Chattanooga, which are, relatively speaking, better off than the surrounding rural counties. But decent housing has always been about affordability. The poorer the region, the harder it is to afford a decent home.

Selvin MaGahee Housing costs are typically the largest single item on a household budget. The initial move-in costs, security and utility deposits, or down payments for homeowners, are often insurmountable hurdles for most people in poverty. Without some type of subsidy these costs easily consume 50 percent or more of the monthly income for someone in poverty. Circumstances become even more extreme with any crisis such as the loss of employment, extended illness, accidents, and so on, often leading to overcrowded extended families or even homelessness. Poverty affects the quality of housing that can be afforded, and most substandard housing, both rented and owned, is occupied by people in persistent poverty.

Bill Bynum: The effects of persistent poverty following the Great Recession point to a widening of gaps within the Mid South that are already too far apart, especially given the relationship between homeownership and wealth accumulation.

Ann Cass: We do a before and after survey of our home owners to measure our success in improving their physical and mental health, children’s progress in school, sociability, and accrual of financial wealth with a new home. It is clear that substandard housing contributes to negative outcomes for all of the above, while new affordable housing make a huge positive difference in the quality of life.

Persistent poverty leads to higher rates of poverty, sicker people due to substandard housing (we are the asthma capitol of the country), separated families, and mental health problems, such as depression and drug and alcohol abuse. The worst result of all this is a sense of hopelessness it brings.

Pinky Clifford: Inadequate financial and management skills results in a lack of motivation to want to move forward no matter where you are in life, as does a lack of sufficient or better housing to create new and safer communities. When we talk about safe communities you have to have adequate services to support the community.

What strategies, solutions, or policies would you recommend to reduce poverty and long-term poverty in your community?

Tom Carew: The War on Poverty has had many successes in Central Appalachia as well as throughout the rest of the US, but our region along with the Delta, Native American lands, and the colonias continue to be the poorest places in America. The regions need to convene and come up with a strategy to collectively move us off the bottom! It is certainly time for us to move these regions forward. Obviously, this is not just a housing issue; it involves all aspects of life and endeavors in the regions. What has seemingly worked for the rest of America has not worked as well for us. How do we create and or shape federal and state policies to better serve the regions and provide the changes we need? This will take academics, activists, economic experts, and community developers.

Selvin MaGahee We must acknowledge and understand that there are distinctly different needs in urban and rural communities. Yet, often the policies and programs implemented at the federal or state level are designed with one-size-fits-all approach. Rural communities are not typically entitlement communities for federal funds like CDBG or HOME, they have to compete – often against the larger urban areas that have more resources and expertise.
crawford-co-bad-house

It is extremely important to design the strategies and policies from a rural perspective. We should make every effort to reduce housing costs, or at least reduce the vast number of households that are cost-burdened. Our state and federal governments should strive to create more affordable housing rather than dismantling successful programs that have worked well for years to help address the problems.

Bill Bynum: Congress and the Administrations should direct 10 percent of any agency’s appropriated funding to counties and parishes that have experienced poverty rates in excess of 20% for 30 years. Enhancing the capacity to help these residents and communities represents one of the most effective strategies for attacking persistent poverty. Investment in CDFIs that have demonstrated track records of bridging the banking gap by connecting underserved populations to safe, affordable financial services is a proven model that builds ladders of opportunity.

Over the last year, HOPE has either experienced, or worked with other credit unions and CDFIs that have experienced a range of responses from banks when closing branches. On one end of the spectrum, one bank that left a community donated a branch to a community development credit union and assisted with transitioning customers from the bank to the credit union. On the other end of the spectrum, a town’s only bank closed its branch and placed a restrictive covenant on the facility that prohibited its use by another financial institution. The Community Reinvestment Act should be strengthened to create more incentives for the first scenario to occur and significant disincentives to prevent the second.

Ann Cass: We are working to help the economic development corporations understand that they have to change the paradigm of what they consider to be economic development. Bringing in new companies, with most of the jobs paying minimum wage, is not economic development.

It is clear to me that we absolutely need to focus on mixed-income neighborhoods and affordable housing. We have to make it possible for people to get out of the colonias. We are watching carefully as cities are working on their development plans. We see they are requiring larger homes in an effort to keep low-income families from living there. We see NIMBYism taking place where housing authorities are prevented from developing units in neighborhoods that are not already blighted with poverty. Those are policies that we are working on.

The bottom line is that we need more affordable housing, rental and ownership. We have 3,800 families on our waiting list and the only thing preventing us from significantly decreasing the list is lack of funding. Building a new house is of course not the only thing needed. I do believe that as housers we need to continue working with the families providing them as many resources from the community that we can. It is our experiment, for better or worse, at getting families from poverty to prosperity.

Pinky Clifford: Federal and nonfederal agencies, corporate entities, foundations and organizations (both public and private), and individuals who want to make change need to look at the map showing poverty in the United States and concentrate on the poorest areas. Combining their resources they could focus on helping us help ourselves. By that, I mean that consultation with leadership would let all of the above know what we need to re-capture the spirit of self-sufficiency. The solution on our side is not simple. Any underserved area has to do a lot of homework in its own strategic planning to assure any entity that we are serious.

Poverty tends to mask the positive in a community. We are proud of our tribal programs and our accredited college, our chamber of commerce, our schools, our nonprofits and other faith-based and community organizations who work hard to provide much needed services to our communities. However, this is a large Reservation and they can’t do it all. We want out of the dark area on the map.

More on Persistent Poverty
To read the contributors’ full interviews, please visit: www.ruralhome.org/revisitingpoverty
GET THE HAC NEWS!

Sign-up for HAC information products

SIGN UP HERE

Housing Assistance Council   |  1828 L Street. N.W., Suite 505, Washington, D.C. 20036
(202) 842-8600  |  (202) 347-3441  |  hac@ruralhome.org |

Board Portal

HAC is an equal opportunity provider, employer, and lender. | Civil Rights | Privacy